Apple’s most expensive iPhone yet is not simply an exercise in premium pricing. It is the consumer-facing consequence of an AI-driven struggle for the world’s memory-chip capacity.
Apple’s unusually expensive launch
Apple’s September product event delivered one message more clearly than any new feature: the iPhone has become significantly more expensive.
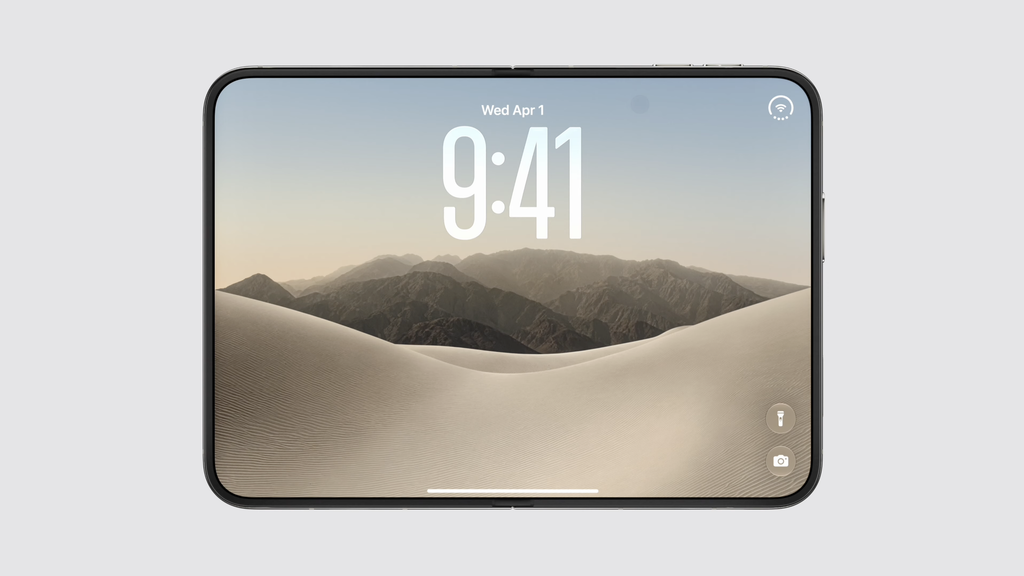
The headline product was the iPhone Duo, Apple’s first foldable phone and the first major launch under its new chief executive, John Ternus. It starts at $1,999 in the US. The 1TB version costs $2,599, while the top 2TB configuration reaches $3,199 — an extraordinary price for a mass-market consumer device and the highest Apple has ever charged for an iPhone.
The iPhone 18 Pro line moved up as well. The Pro starts at $1,199 and the Pro Max at $1,299, both $100 above their predecessors. At the top end, the 2TB Pro Max costs $2,499. Apple also raised prices on several older models still in its line-up.
But another announcement complicates the obvious explanation. The AirPods 5 became cheaper. The new model brings active noise cancellation to a $129 starting price, below the $179 launch price of the noise-cancelling AirPods 4.
That contrast matters. If Apple were simply using its brand power to push prices higher across the board, AirPods would have little reason to move in the opposite direction. Instead, the steepest increases are concentrated in products that require substantial amounts of memory and storage — and the increases become more severe at higher capacities.
This is not just a premiumisation story. It is a supply-chain story.
A “100-year flood” in memory prices
Before stepping down as chief executive, Tim Cook offered an unusually stark description of the problem.
“On the pricing front, we reluctantly raised prices,” he said during Apple’s third-quarter earnings call. “We did it because we’re in what I would characterise as a 100-year flood on the memory pricing, with exponential increases in memory prices.”
Cook is not known for dramatic language. His reputation was built on the opposite: disciplined operations, minimal inventory and relentless pressure on suppliers. Apple’s traditional playbook has been simple and highly effective. It uses enormous order volumes to negotiate lower prices, then brings in alternative suppliers to prevent any one company from gaining too much leverage.
For decades, that model helped turn Apple’s supply chain into a competitive advantage. This time, even Apple is struggling to make it work.
The balance of power has shifted because the global memory market is exceptionally concentrated. According to Counterpoint Research, Samsung held 38% of the DRAM market by revenue in the second quarter of 2026, followed by SK hynix with 25% and Micron with 24%. Together, the three companies controlled 87% of the market. In high-bandwidth memory, or HBM — the advanced memory used alongside AI accelerators — the same three suppliers account for almost the entire market.
In a fragmented industry, Apple can play suppliers against one another. In an oligopoly with tight capacity, suppliers can make Apple compete for allocation.
Micron’s chief business officer, Sumit Sadana, made the reversal unusually explicit. Discussing the previous memory downturn, he said some customers had pushed for “rock-bottom prices” at a time when suppliers’ margins were collapsing.
“We told a couple of the customers who were being very aggressive with pricing at that time that this is not constructive,” Sadana said, without naming Apple. “A lot of the industry investments got shut down in 2023 because of really poor pricing and really poor margins.”
His argument was pointed: years of aggressive procurement helped weaken the incentive to invest in new capacity. Now the customers that benefited from low prices are confronting the consequences.
AI has rewritten the economics of memory
The immediate cause of the shortage is the AI infrastructure boom.
AI servers require enormous quantities of memory, particularly HBM. A typical AI server can contain many times the memory of a conventional server, and demand is rising as models grow larger, context windows expand and inference workloads spread.
Memory manufacturers therefore face a straightforward economic choice. They can devote capital and production resources to conventional DRAM used in phones and PCs, or prioritise higher-margin products for AI data centres. Unsurprisingly, they are favouring AI.
HBM is not simply ordinary phone memory with a different label. It requires advanced stacking and packaging, and it consumes substantially more manufacturing capacity per bit. But the two products still compete for parts of the same finite ecosystem: wafers, clean-room space, equipment, engineers and capital expenditure. Every additional commitment to HBM makes it harder to expand the supply of conventional DRAM at the same time.
That is why the AI boom can create shortages far beyond AI itself. TrendForce estimates that HBM and server RDIMM will account for 51% of DRAM bit supply in 2026. Suppliers have also redirected NAND capacity towards enterprise SSDs, which serve data centres, rather than lower-margin consumer products.
The result is a powerful feedback loop. Tight supply supports high prices. High prices produce exceptional profits. Those profits fund the next generation of advanced memory capacity, reinforcing the technological and financial advantage of the market leaders. The more dominant the top suppliers become, the greater their ability to dictate terms.
That does not prove illegal co-ordination. But the structure has attracted regulatory and legal scrutiny. In June, consumers and small PC businesses filed a proposed class action in a California federal court, accusing Samsung, SK hynix and Micron of using the shift towards HBM as cover for restricting commodity DRAM supply. The complaint alleges that DRAM prices rose by roughly 700% over four years. These remain allegations, not established facts, but they capture the suspicion surrounding a market in which three companies control almost all supply.
The hidden AI surcharge on consumer technology
For consumers, the crucial question is how this shortage travels through the supply chain.
The numbers are striking. Industry estimates cited in reporting on the iPhone 18 Pro put the cost of a 12GB mobile DRAM package at about $145, up from roughly $39 a year earlier. A 256GB NAND package rose from around $13 to $51. TrendForce estimates that memory costs for the 256GB iPhone 18 Pro are nearly four times higher than for the equivalent model a year ago.
Memory once represented about 10% of an iPhone Pro’s bill of materials. By the third quarter of 2026, its share had climbed to approximately 34%, overtaking components that historically dominated the cost structure, such as the application processor. TrendForce expects memory’s share to exceed 40% in the first half of 2027 if current conditions persist.
At that point, Apple has only three options: accept lower margins, reduce specifications or charge customers more. It appears to be doing some combination of all three, but price increases are now unavoidable.
The pressure is not limited to smartphones. PC makers have raised prices or reduced memory configurations. Qualcomm has increased chip prices. Samsung, despite being one of the world’s largest memory manufacturers, has also passed higher costs into its own devices.
The effect has even reached the car industry. Modern electric vehicles use large amounts of DRAM and NAND for infotainment, driver assistance and central computing. Nio said rising memory, battery and raw-material costs increased its average cost by more than RMB10,000 — about $1,400 — per vehicle in the second quarter, with the impact reaching roughly RMB14,000, or $2,000, in the following quarter.
The exact specifications differ across phones, computers and cars. The underlying constraint does not: they all compete for output from a highly concentrated memory industry whose most profitable customers are now AI data centres.
This creates what amounts to a hidden AI surcharge on ordinary technology. Consumers buying a phone, laptop or car are indirectly paying for the resources being pulled into the AI infrastructure build-out.
Apple’s search for an alternative
Apple’s traditional answer to supplier power is diversification. Its latest attempt centres on ChangXin Memory Technologies, better known as CXMT, China’s leading DRAM manufacturer.
Apple has tested CXMT chips across several product lines, including iPhones and MacBooks, and has held preliminary talks about using them in devices sold in China, according to reporting by The Wall Street Journal and Reuters. Strategically, the logic is clear: a fourth supplier could reduce Apple’s dependence on Samsung, SK hynix and Micron.
But CXMT is not a simple low-cost substitute. Its capacity is already tight, it remains behind the market leaders in some technologies, and reports suggest it has been unwilling to offer the steep discount Apple expected. In a seller’s market, even a rising challenger has little reason to undercut incumbents aggressively.
There are also geopolitical complications. Any move by Apple towards Chinese memory would face scrutiny in Washington, while US export controls limit some forms of technology transfer and technical collaboration with CXMT. Apple may be able to use standardised components in China-market devices, but creating a deeply integrated global supply relationship would be far more difficult.
In other words, Apple’s Plan B exists, but it cannot solve the immediate problem.
The shortage will outlast this iPhone cycle
New semiconductor capacity takes years to build. A memory fab requires vast capital investment, advanced equipment, lengthy qualification and time to improve yields. Announced projects will eventually add supply, but they cannot relieve a shortage within a few quarters.
Meanwhile, much of the industry’s 2027 capacity has already been allocated through long-term agreements. Reports suggest that some customers are receiving only 60% to 70% of the volumes they requested. Securing supply — not negotiating the lowest price — has become the priority.
That means the iPhone’s price increase is unlikely to be a one-off event. Elevated memory costs could persist through 2027 and potentially longer, especially if AI infrastructure investment continues at its current pace.
Seen in isolation, the $3,199 iPhone Duo looks like the latest example of Apple testing the limits of what loyal customers will pay. Seen through the supply chain, it tells a more important story.
AI data centres are absorbing a growing share of the world’s memory resources. Three suppliers hold extraordinary pricing power. Apple, usually the strongest negotiator in consumer electronics, has been forced onto the defensive. The cost then moves downstream — into smartphones, computers, cars and, ultimately, household budgets.
The AI boom is often described in terms of chips, models and capital expenditure. Its less visible consequence is a reallocation of physical resources across the entire technology economy. The most expensive iPhone in history is one of the first consumer products to make that cost impossible to ignore.